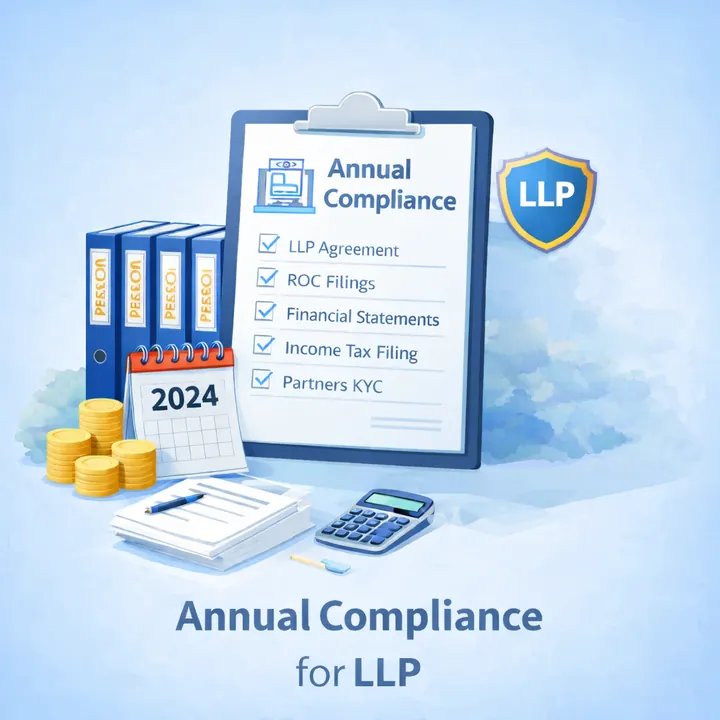
LLP annual compliance comes down to two MCA forms and one tax return: Form 11, the annual return, within 60 days of the year end (30 May), Form 8, the Statement of Account and Solvency, by 30 October, and ITR-5, due 31 August if the accounts need no audit or 31 October if they do. For FY 2025-26 the audited ITR date is 21 November 2026. A late Form 8 or Form 11 can draw a penalty of ₹100 a day, up to ₹1 lakh for the LLP.
What LLP annual compliance involves
Every LLP keeps books, prepares a Statement of Account and Solvency, files it and its annual return with the Registrar, and files an income tax return. All of it applies whether the LLP traded or not, and the designated partners answer for it.
| Filing | What it reports | Due | Signing |
|---|---|---|---|
| Form 11 | Registered office, business activity, partners and designated partners | 30 May | A designated partner, with a certificate from another designated partner or, for larger LLPs, a CS in practice |
| Form 8 | Solvency declaration, plus assets, liabilities, income and expenditure | 30 October | The designated partners, after an audit where one applies |
| ITR-5 | Income, deductions and tax | 31 August or 31 October | Filed online; with a digital signature if a tax audit applies |
Two event-based duties run through the year: a partner joining or leaving, or changing name or address, is reported to the Registrar within 30 days (section 25(2) of the LLP Act), and designated partners with a DIN complete DIR-3 KYC once every three years, next by 30 June 2028.
LLP Form 11 filing: the annual return due 30 May
Form 11 is the LLP's annual return under section 35 of the LLP Act 2008, filed within 60 days of the close of the financial year. It records the position as at 31 March: registered office, principal business activity and a summary of partners and designated partners.
Under rule 25(2) of the LLP Rules 2009, an LLP with turnover up to ₹5 crore or contribution up to ₹50 lakh attaches a certificate from a designated partner other than the one signing. Every other LLP needs a certificate from a company secretary in practice who has checked the particulars against the books. Form 11 falls due five months before Form 8, so it cannot wait for the accounts to be finalised.
LLP Form 8 filing: statement of account and solvency due 30 October
The designated partners must prepare the Statement of Account and Solvency within six months of the year end, and file it in Form 8 within 30 days after that, which makes the deadline 30 October (section 34 and rule 24). In it they declare whether the LLP can pay its debts in full as they fall due.
- Books. Kept on cash or accrual basis under double entry at the registered office (section 34(1)) and preserved for eight years (rule 24(3)).
- Audit. Required above ₹40 lakh turnover or ₹25 lakh contribution under rule 24(8); the audit applicability checker explains the test. The auditor must be a chartered accountant in practice, appointed at least 30 days before the year ends.
- No audit. The partners include a statement in Form 8 acknowledging their responsibility for the books.
LLP ITR: form, due dates and tax rate
An LLP files ITR-5, the form the Income Tax Department lists for firms and LLPs for AY 2026-27. It is due by 31 August when the accounts need no audit, or 31 October when they do, and CBDT Circular 07/2026 moved the audited date for FY 2025-26 to 21 November 2026.
- Tax audit. Separate from the LLP Rules audit: it applies when business turnover exceeds ₹1 crore (₹10 crore if cash receipts and payments are each 5% or less) or professional receipts exceed ₹50 lakh.
- Rate. 30% plus 4% cess, which is 31.2%, and 34.944% once income exceeds ₹1 crore and the 12% surcharge applies. LLPs cannot use the presumptive scheme open to individuals and ordinary firms.
- Partner payments. Remuneration is deductible only for working partners, only if the LLP agreement allows it, and only within limits based on book profit (section 35(e) of the Income-tax Act 2025, section 40(b) of the 1961 Act). Since 1 April 2025 the LLP deducts 10% TDS once a partner's remuneration, interest or similar payments exceed ₹20,000 in a financial year.
The business tax comparison calculator shows how the remuneration limit changes an LLP's tax bill.
Who needs LLP annual compliance, even without business
Every registered LLP files Form 11, Form 8 and ITR-5 each year, including one with no income. India had 5,06,315 active LLPs on 13 July 2026, according to a Lok Sabha reply of 20 July 2026, and each owes the same three filings.
Example. Brightwater Design LLP (a made-up firm) was incorporated on 12 November 2025. Because that is after 30 September, its first financial year may run to 31 March 2027 (section 2(1)(l)). If it takes the longer period, its first Form 11 is due by 30 May 2027 and its first Form 8 by 30 October 2027, though income tax still runs on the April to March year.
An LLP that has carried on no business for a year or more can apply to the Registrar in Form 24 to strike off its name, with a fee of ₹500 for a small LLP and ₹1,000 for others. Overdue Form 8 and Form 11 usually have to be filed first; see LLP winding up.
Penalties and late fees for missed LLP filings
A late Form 8 or Form 11 attracts two separate costs: an additional fee that is a multiple of the normal filing fee, and a penalty. The MCA late fee calculator works out the additional fee from your contribution and the number of days.
- Late filing penalty. ₹100 a day for the LLP and for its designated partners, up to ₹1 lakh for the LLP and ₹50,000 for each designated partner (sections 34(5) and 35(2)).
- Books, statement or audit not done. A fine of ₹25,000 to ₹5 lakh on the LLP and ₹10,000 to ₹1 lakh on each designated partner (section 34(6)).
- Partner change not reported. ₹10,000 on the LLP and each designated partner (section 25(4)).
- Relief. No penalty is imposed if a late Form 8 or Form 11 is filed before, or within 30 days of, the adjudicating officer's notice, and a small or recognised start-up LLP pays half, capped at ₹1 lakh and ₹50,000 (section 76A).
Common mistakes in LLP annual filing
Most LLP defaults come from treating the LLP like an informal partnership. These are the ones that cost money.
- Skipping Form 8 and Form 11 in a year with no business.
- Crossing ₹40 lakh turnover mid-year without appointing an auditor; rule 24(11) lets the designated partners fill the vacancy.
- Paying remuneration the LLP agreement does not authorise, which makes it non-deductible.
- Missing the 10% TDS on partner payments above ₹20,000.
- Reporting a new partner only in Form 11 months later, instead of within 30 days.
How Ofin handles LLP annual compliance
Ofin's CAs and CSs keep the LLP's accounts (for turnover up to ₹10 lakh in the base package), file Form 11, Form 8 and the ITR, and assign a dedicated accountant for the year. Higher packages add DIR-3 KYC for two designated partners and periodic GST and TDS returns. Everything is online, with a reply within 24 hours. Fees start at ₹7,999. Get a fixed-price proposal.