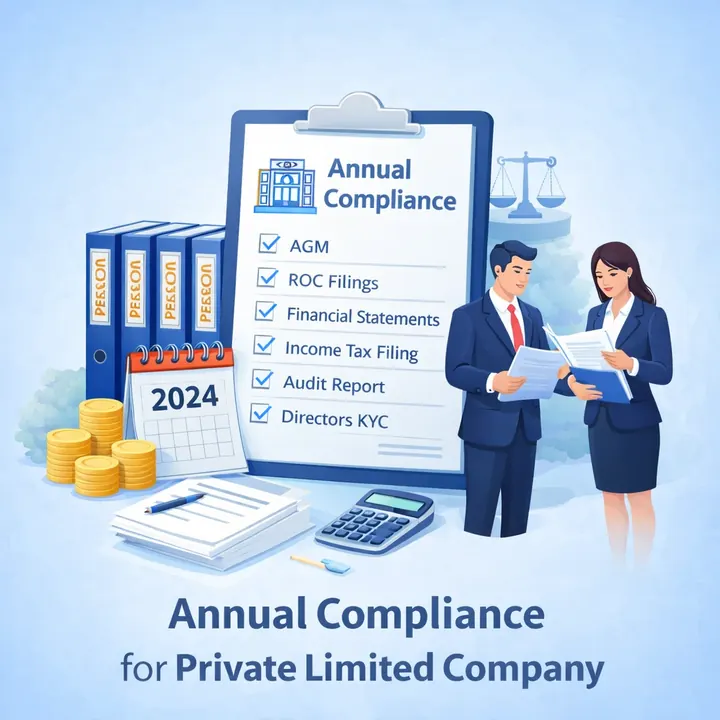
Annual compliance for a private limited company is a yearly cycle of audit, meetings and filings: a chartered accountant audits the accounts, the Board meets at least four times (twice for a small company), the AGM adopts the accounts, and the company files AOC-4 within 30 days and MGT-7 or MGT-7A within 60 days of that AGM, then its ITR-6 tax return. For FY 2025-26 the AGM was due by 30 September 2026 and the tax return is due by 21 November 2026 (30 November with a transfer pricing report). Every company owes this, including one that did no business.
What annual compliance for a private limited company includes
It has four layers: the statutory audit, the meetings that approve the accounts, the ROC annual filing and the tax return. Each rests on a specific section of the Companies Act 2013 or tax law.
| Item | What it involves | Basis |
|---|---|---|
| Statutory audit | A chartered accountant audits the accounts, whatever the turnover | Section 139 |
| Board meetings | At least four a year, not more than 120 days apart; a small company or OPC needs one in each half of the calendar year, at least 90 days apart | Section 173 |
| Interest disclosures | Each director discloses interests in other entities at the first Board meeting of every financial year | Section 184(1) |
| AGM | Adopts the audited accounts within 6 months of the year end | Section 96 |
| AOC-4 | Financial statements, with the Board's report and auditor's report | Section 137 |
| MGT-7 or MGT-7A | Annual return on shareholding, directors and meetings | Section 92 |
| ITR-6 | Company tax return, with a tax audit report if turnover exceeds ₹1 crore (₹10 crore if cash receipts and payments are each 5% or less) | Income-tax Act |
Conditional filings sit on top: ADT-1 when an auditor is appointed, DPT-3 for loans or deposits, MSME-1 for dues to micro or small suppliers older than 45 days, and DIR-3 KYC once every three years. The ROC compliance calendar turns these into dates.
AOC-4 and MGT-7 filing: what each form reports
AOC-4 carries the financial statements adopted at the AGM, and MGT-7 is the annual return describing the company as at the close of the financial year. Small companies and OPCs file the shorter MGT-7A. Both are filed online on the MCA21 portal.
- AOC-4 attaches the auditor's report and the Board's report. Since 14 July 2025, extracts of both reports are filed with it. If the AGM does not adopt the accounts, the unadopted statements are still filed within 30 days and held as provisional (section 137(1)).
- MGT-7 reports the registered office and business activity, shares and shareholding, members, directors and key managerial personnel, meetings with attendance, directors' remuneration and any penalties. A director and the company secretary sign it; without a company secretary, a CS in practice signs. A small company or OPC without a company secretary can have it signed by a director alone.
- If no AGM is held, the filings are still due, within 30 and 60 days of the last date the AGM should have been held, with a statement of reasons (sections 92(4) and 137(2)).
Who needs ROC annual filing, even with no business
Every company registered under the Companies Act 2013 files its accounts and annual return each year, whether or not it traded. A company with no business has only two formal exits from the yearly cycle: dormant status under section 455, or closure.
Non-filing is widespread. In a reply to Lok Sabha Unstarred Question 146 on 20 July 2026, the Ministry of Corporate Affairs said 6,64,576 of the 17,65,176 companies due to file for FY 2024-25 had not filed their annual returns, and that a company in default for over two years can be struck off.
- Dormant status. A company formed for a future project or to hold an asset, or an inactive one (no business, no significant transactions, or no accounts and annual returns in the last two financial years), can apply to the Registrar, then keeps the status by filing prescribed documents and an annual fee.
- Closure. A company with no business for two years can apply to strike off its name; the close your company finder compares the routes.
Documents needed for annual compliance
Most of the effort is in the accounts, so the list starts with the books. Ofin collects these online for your accountant and auditor.
- Books of account, all bank statements, and sales, purchase and expense records
- GST returns and TDS statements filed during the year, to reconcile turnover and tax
- The fixed asset list, loan agreements and details of money received from directors or others
- Share allotments or transfers during the year and the list of shareholders on 31 March
- Board minutes, directors' interest disclosures, and each director's DIN and digital signature
- Amounts owed to micro or small suppliers for more than 45 days
Step-by-step annual compliance process
The process runs from closing the books to the tax return, and each step waits for the one before it, so a late audit delays every filing.
- Close the books for the year ending 31 March and prepare the financial statements.
- The Board approves them, and two directors (or the authorised chairperson) sign them for the auditor (section 134(1)).
- The auditor audits the accounts and signs the audit report.
- The Board approves its report and calls the AGM with at least 21 clear days' notice, or shorter notice if 95% of the members entitled to vote agree (section 101).
- The AGM adopts the accounts. At the first AGM it appoints an auditor until the sixth AGM, and ADT-1 follows within 15 days (section 139).
- File AOC-4 within 30 days and MGT-7 or MGT-7A within 60 days of the AGM.
- File the tax audit report, where needed, and ITR-6.
The AGM due date calculator shows how the 15-month gap between meetings can bring your AGM date forward.
What annual compliance costs and what late filing adds
The cost has three parts: MCA filing fees of ₹200 to ₹600 per form depending on nominal share capital, your auditor's fee, and the professional fee for preparing and filing, which at Ofin starts at ₹19,999. Late filing adds two separate charges.
- Additional fee. It accrues each day an AOC-4 or annual return stays unfiled; the MCA late fee calculator gives the exact amount.
- Penalty. An adjudicating officer can also impose ₹10,000 plus ₹100 a day, up to ₹2 lakh on the company and ₹50,000 on each officer in default (sections 92(5) and 137(3)). Small companies, OPCs and recognised start-ups pay at most half, capped at ₹2 lakh and ₹1 lakh (section 446B).
Watch out. Under the proviso to section 454(3), added by the Companies (Amendment) Act 2020, no penalty is imposed for a late annual return or AOC-4 if the default is fixed before, or within 30 days of, the adjudicating officer's notice. Late is still far better than never.
What happens if a company skips annual compliance
Beyond fees, skipping years puts the directors and the company at risk: disqualification of every director and removal of the company from the register.
- Director disqualification. If a company does not file its financial statements or annual returns for any continuous period of three financial years, its directors cannot be reappointed there or appointed to any other company for five years (section 164(2)(a)).
- Strike off by the ROC. The Registrar can remove a company that has carried on no business for the two preceding financial years without applying for dormant status (section 248(1)(c)).
- Dormant register. A company that has not filed accounts or annual returns for two consecutive years can be entered in the register of dormant companies after a notice (section 455(4)).
Changes in 2025 and 2026 to plan for
Several changes since 2025 alter who files what. Most reduce the burden, but one relief scheme has closed.
- Small company limits. Paid-up capital up to ₹10 crore and turnover up to ₹100 crore from 1 December 2025 (G.S.R. 880(E)), so more companies file MGT-7A, hold two Board meetings a year and face halved penalties.
- Director KYC. Once every three years by 30 June since 31 March 2026, with the next date 30 June 2028 (PIB release), not every 30 September.
- Tax return. CBDT Circular 07/2026 moved the FY 2025-26 date for audit cases to 21 November 2026, and the tax audit report to 21 October 2026.
- Relief scheme. The CCFS 2026 waiver window for old filings closed on 15 September 2026.
- Proposal only. The Corporate Laws (Amendment) Bill 2026 would cap additional fees at ₹2 lakh for classes of companies to be prescribed; it is not yet law.
How Ofin handles your company annual compliance
Ofin's CAs, CSs and legal professionals run the whole cycle online: bookkeeping and financial statements, AGM papers, then AOC-4, MGT-7A, ADT-1, INC-20A where due, directors' KYC and ITR-6. Larger packages add GST, TDS, PF and ESI returns. Fees start at ₹19,999.
We reply within 24 hours, and for pending years we confirm the additional fee before filing. Get a fixed-price proposal.